Fire Risk Assessments for Student HMOs in Manchester: A Landlord’s Guide
22/09/2026
Manchester has one of the largest student populations of any city in the UK, with more than 100,000 students living and studying across the city each year. A huge share of them live in shared houses in multiple occupation (HMOs) in areas like Fallowfield, Rusholme, Withington and Victoria Park, and every September a fresh wave of tenants moves into properties they’ve never set foot in before.
That turnover is exactly what makes student HMOs one of the highest-risk property types for fire safety. New tenants each year, high occupancy, shared kitchens, and a growing habit of charging e-bikes and scooters overnight all add up to a property type that needs proper, documented fire risk management, not a box-ticking exercise done once and forgotten.
If you let, manage or invest in student HMOs anywhere in Manchester, here’s what you actually need to know about fire risk assessments: when you need one, what Manchester’s licensing rules mean for you, what a good assessment should cover, and where landlords most often get caught out.
Student properties aren’t just ordinary shared houses with younger tenants. Several factors combine to push the fire risk higher than in most other rented accommodation.
Most student tenancies run for a fixed academic year, which means a large proportion of Manchester’s student HMOs change over completely every summer. New occupants don’t know the layout, don’t know where the fire alarm panel is, and haven’t been shown the escape routes. Greater Manchester Fire and Rescue Service specifically flags this as a risk period in its own student safety guidance, which stresses that students in flats should “know the evacuation plan for your building” before anything goes wrong.
Cooking remains one of the most common causes of accidental house fires in the UK, and GMFRS names distracted cooking and cooking under the influence of alcohol as two behaviours it specifically warns students about. A shared kitchen used by four, five or more unrelated tenants multiplies the chances of a pan being left unattended.
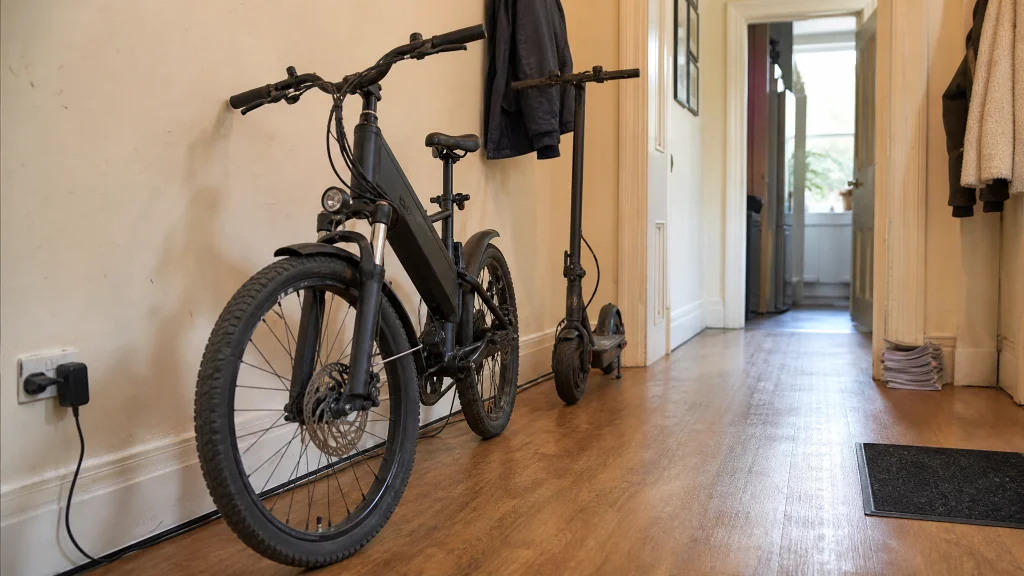
Battery-powered transport has become standard kit for students getting around a spread-out campus city, and charging habits haven’t caught up with the risk. We’ve covered the mechanics of lithium-ion battery fire hazards in detail elsewhere, but the short version for student HMOs is this: a battery charging unattended overnight in a hallway or bedroom, especially a cheap or damaged one, can turn from smouldering to full fire in under a minute, and it usually happens while everyone’s asleep.
I see the same gap repeatedly in student HMO assessments: everything looks compliant on paper from the last academic year, but nobody’s re-briefed the new tenants who moved in three weeks ago. A fire risk assessment that isn’t refreshed at the same pace as the tenancy turnover isn’t protecting anyone.
Converted terraced houses, common across Fallowfield, Rusholme and Withington, often have irregular layouts: narrow staircases, back extensions, loft conversions, and kitchens that were never designed to be shared by five or six people. A new tenant who’s lived there for three weeks is far less likely to know the quickest way out than someone who’s lived in a property for years.
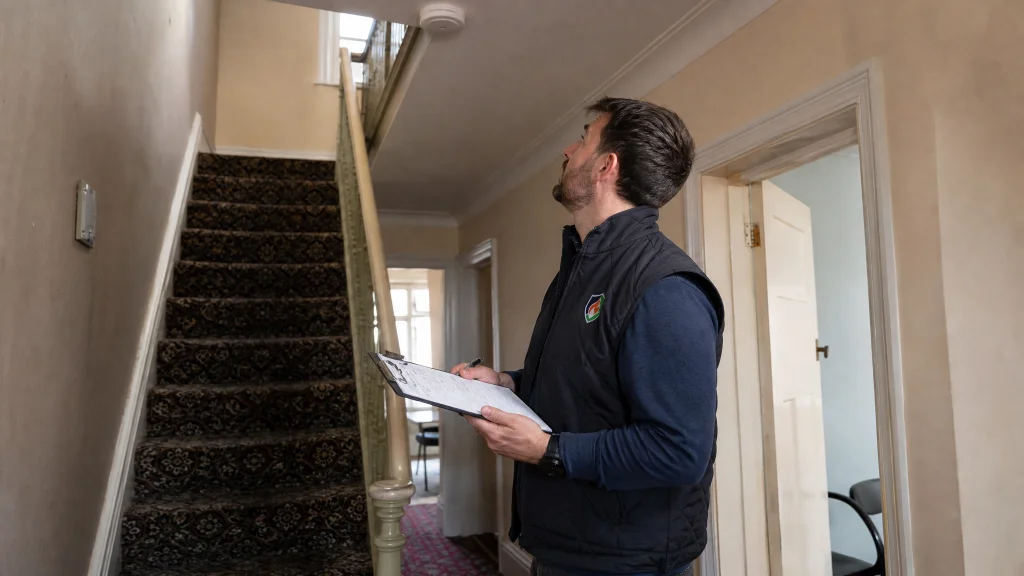
Fallowfield, Rusholme, Withington and Victoria Park share a housing stock problem that makes fire safety harder to manage than in a purpose-built student development. Most of the properties are Victorian or Edwardian terraces, originally built as single-family homes, later carved up into shared lets with an extra bedroom fitted into what used to be a dining room or a loft.
That conversion history matters for fire safety in a very practical way. These houses typically have one staircase, not two, which means there’s usually only one realistic way out if a fire starts in the hallway or stairwell. Later additions, like a rear kitchen extension or a loft conversion bedroom, often weren’t built with fire-resistant construction or a protected escape route in mind, because at the time they were built the house was still a single-family home, not five bedrooms let separately to strangers.
None of this makes these properties unsafe by default, but it does mean the fire risk assessment has to look closely at the actual layout rather than following a generic checklist. A loft conversion bedroom with a single small window and no protected staircase needs a very different set of recommendations to a ground-floor room next to the front door, and a good assessor working across Fallowfield or Rusholme regularly will already be familiar with exactly this kind of layout.
Yes, in almost every case. The legal duty to carry out a fire risk assessment comes from the Regulatory Reform (Fire Safety) Order 2005 (RRFSO), not from HMO licensing. Manchester City Council’s own guidance for HMO landlords is direct on this: “landlords of Houses in Multiple Occupation (HMO) must ensure that a fire risk assessment is made of the common areas, by a competent person.”
This duty applies regardless of whether the property needs an HMO licence. It’s a common misconception among smaller student-house landlords that a 3 or 4-bedroom shared house without a licence is somehow outside the fire safety rules. It isn’t. The RRFSO duty sits on top of, and separate from, whatever licensing regime applies.
Under the official government definition, a property is an HMO if at least three tenants live there forming more than one household, and they share a toilet, bathroom or kitchen. A large HMO is one with five or more tenants forming more than one household with shared facilities, and it’s this five-tenant threshold, set nationally since October 2018, that triggers mandatory HMO licensing from the local council.
| Property type | Typical example | Fire risk assessment required? | HMO licence required? |
|---|---|---|---|
| Small shared student house | 3-4 students sharing a kitchen and bathroom | Yes, under the RRFSO, regardless of licensing status | Only if the property falls within a council-designated licensing area; check street-level status with the council |
| Large student HMO | 5+ students forming 2+ households sharing facilities | Yes, under the RRFSO | Yes, mandatory HMO licence required from Manchester City Council |
| Purpose-built student flats (self-contained) | Individually self-contained studio or cluster flats in a block of 3+ units | Yes, for the building’s common parts (managed by the building’s responsible person) | Usually exempt from HMO licensing if genuinely self-contained and purpose-built |
| Converted house split into bedsits | Shared amenities, non-self-contained rooms | Yes, under the RRFSO | Yes if 5+ tenants forming 2+ households; check for additional licensing locally |
The practical takeaway: don’t use occupancy numbers alone to decide whether fire safety law applies to you. It almost always does. Licensing decides whether you need a certificate from the council; the RRFSO decides whether you’re legally required to manage fire risk, and that applies from the very first tenant.
Manchester City Council has operated mandatory HMO licensing since October 2018, requiring a licence for any property occupied by five or more people forming two or more households who share basic amenities. Manchester also runs selective licensing schemes on specific streets, including parts of Rusholme, Moss Side, Longsight, Crumpsall and Cheetham, which apply to privately rented properties on those streets regardless of whether they’re an HMO. Coverage is set street by street rather than ward-wide, so the only reliable way to check a specific property is through the council’s own address lookup rather than assuming an entire postcode or neighbourhood is covered.
If you’re weighing up whether licensing and fire safety compliance are worth the admin, the numbers have moved sharply against skipping it. Under the Renters’ Rights Act, the maximum civil penalty for operating an unlicensed HMO or breaching licence conditions rose from £30,000 to £40,000 from 1 May 2026. Councils can also pursue rent repayment orders, recovering up to two years of rent for an unlicensed property, and this now extends to superior landlords in rent-to-rent arrangements, not just the person named on the tenancy.
A recent national example shows how these penalties stack up in practice. In a case reported in February 2025, a landlord operating an unlicensed nine-occupant HMO was fined a total of £14,556 after a council investigation found a non-functional fire alarm system, inadequate escape routes, and fire doors that had deteriorated and no longer provided proper fire resistance. Individually, each fire safety breach attracted its own separate penalty on top of the unlicensed HMO fine. For more on what tends to happen when landlords skip this step entirely, we’ve covered the wider consequences in what happens if you don’t have a fire risk assessment.
Under the RRFSO, the responsible person for a rented HMO is usually the landlord, though it can be a managing agent or another party with control of the premises. Since October 2023, responsible persons have had additional legal duties: recording the fire risk assessment in writing, documenting who carried it out, identifying any other responsible persons in a multi-occupied building (such as a managing agent for a converted block), and passing on fire safety information if the property is sold or the management changes hands. For student HMOs specifically, this written record matters more than most property types, because a verbal handover doesn’t survive an annual tenant turnover.
A large share of Manchester’s student HMOs are managed day to day by a letting agent rather than the landlord directly, and this is one of the most common points of confusion when something goes wrong. The RRFSO’s “responsible person” can be the landlord, the managing agent, or in some cases both, depending on who actually has control of the premises in practice.
If you use a managing agent, get it in writing who is responsible for commissioning and reviewing the fire risk assessment, who holds the written record, and who is responsible for briefing tenants at the start of each tenancy. A verbal understanding that “the agent sorts the fire safety stuff” isn’t a defence if the agent hasn’t actually done it, and as the freeholder or head tenancy holder you can still be pursued as a responsible person even where day-to-day management sits with someone else. This is exactly the kind of gap the October 2023 changes were designed to close, by requiring responsible persons to identify each other in writing rather than assuming someone else has it covered.
If you hold several student HMOs across Fallowfield, Rusholme, Withington and Victoria Park through different agents, it’s worth keeping a single master record of which property has a current fire risk assessment, who carried it out, and when it’s due for review, rather than relying on each agent to flag it separately. Properties fall out of compliance most often when management responsibility is genuinely unclear rather than because anyone deliberately ignored it.
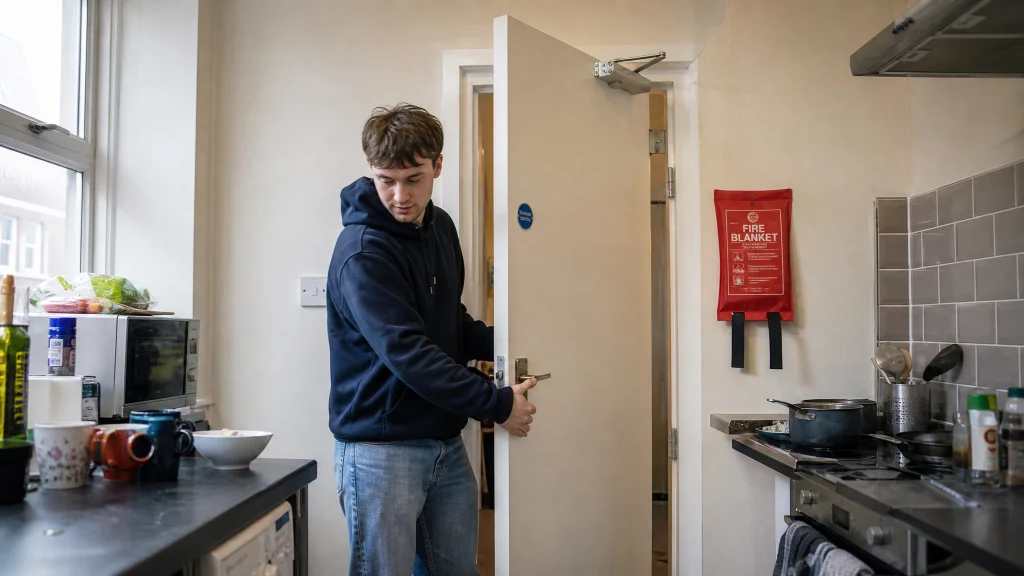
A generic template won’t cut it for a property that changes occupants every year. A proper assessment for a student HMO should specifically address:
The properties that fail inspections aren’t usually missing equipment entirely. It’s more often a fire door that’s been propped open with a shoe because it’s hot in the kitchen, or a smoke alarm that’s been disconnected because it kept going off from toast. Those are five-minute fixes if you catch them, but they’re exactly what an assessor is trained to look for and what most landlords walk straight past.
Most student HMOs in Manchester turn over their entire tenant base within the same few weeks every September. That creates a genuine spike in risk that doesn’t apply to most other rented property types, and it’s worth planning for specifically rather than treating fire safety as a once-a-year admin task done at a random point in the calendar.
Walk the property and check every fire door still closes and latches properly, test every smoke and heat alarm, and confirm the escape route is genuinely clear, not just clear of last year’s tenants’ belongings but structurally unobstructed.
This is when unfamiliarity is at its highest. A written fire safety briefing at the start of the tenancy, covering the evacuation plan, alarm locations, and charging arrangements for e-bikes and scooters, closes the single biggest gap between “the property is compliant” and “the tenants actually know what to do.”
Across the fire risk assessments carried out on shared houses in the city, the same handful of issues come up again and again. If you manage a student HMO, these are worth checking before an assessor or a council inspector finds them for you:
Beyond the civil penalties and rent repayment orders already covered above, a fire risk assessment that’s missing, out of date, or ignored has consequences that go further than a council fine. Most landlord insurance policies for HMOs are conditional on the property meeting current fire safety regulations, and a documented, in-date fire risk assessment is usually the first thing an insurer asks to see after any fire-related claim. A policy that looks fully paid up can still be void at the point of claim if the insurer can show basic fire safety measures weren’t in place, which for a portfolio landlord can mean one missing assessment putting far more than a single property’s cover at risk. In the worst cases, a fire in an occupied HMO with inadequate fire safety measures can lead to prosecution under the RRFSO itself, which sits alongside and separate from any HMO licensing penalty.
For landlords weighing up the actual cost of getting this right, we’ve broken down typical pricing in our guide to fire risk assessment costs for HMO landlords, and it’s consistently far lower than the penalties above.
There’s no single fixed legal interval written into the RRFSO, but the standard guidance is to review annually as a minimum, and sooner if anything material changes. For student HMOs specifically, that annual point should line up with the tenant changeover rather than an arbitrary date, because a review that happens mid-tenancy tells you less about the risks the incoming tenants will actually create.
You should also review sooner than the annual point if there’s been any building work, a near-miss or actual fire incident, a change to the layout or number of tenants, or if a previous assessment flagged actions that haven’t yet been completed. An assessment that’s sitting in a drawer with unresolved actions from eighteen months ago isn’t doing its job, whatever the calendar says.
Yes. The duty comes from the Regulatory Reform (Fire Safety) Order 2005 and applies to the common areas of any HMO, regardless of whether the property is small enough to fall outside mandatory HMO licensing. A 3-bedroom shared student house still needs one.
Not under Manchester’s mandatory scheme, which applies to properties with five or more tenants forming two or more households. However, if the property sits on a street covered by Manchester’s selective licensing scheme, a licence may still be required regardless of size, so check the specific address with the council rather than assuming.
Pricing depends on the size and layout of the property, but it’s a fixed, one-off cost that’s typically a fraction of the civil penalties involved in non-compliance. See our full cost breakdown for current typical pricing.
The “responsible person” under the RRFSO, which is usually the landlord, but can be a managing agent where one has been given control of the property. This person must arrange the assessment, keep a written record, and act on any actions it identifies.
Two things combine to push the risk above other property types: the annual full turnover of tenants who don’t know the building, and the growing use of e-bikes and e-scooters charged unattended, often overnight and often in bedrooms or hallways.
The RRFSO requires the assessment to be carried out by a “competent person.” For a straightforward single-let this might be the landlord themselves if genuinely competent to do it, but for a multi-occupied student HMO with shared escape routes and multiple fire safety systems, most landlords use a qualified assessor, both for the quality of the assessment and to demonstrate competence if the assessment is ever challenged.
Having a current, documented fire risk assessment won’t usually reduce your premium directly, but not having one can void your cover entirely when it matters most, at the point of a claim. Insurers increasingly ask for evidence of an in-date assessment as a condition of cover for HMOs, so it’s worth checking your policy wording rather than assuming it isn’t required.
For a standard 4 to 6-bedroom converted terrace, the on-site inspection usually takes an hour or two depending on the layout and number of floors, with the full written report and action plan following afterwards. Larger properties or those with more complex escape routes take longer to assess properly.
If you manage student HMOs anywhere in Manchester, whether that’s a single house in Fallowfield or a portfolio spread across Rusholme, Withington and beyond, getting the fire risk assessment right at the start of each academic year is the single biggest thing you can do to protect your tenants and your licence. Get in touch for a fire risk assessment quote, or find out more about our fire risk assessment services across Manchester.
Most HMO landlords I talk to can rattle off their fire door requirements, their alarm grade, and their emergency lighting checks without missing a beat....
Most of the fire safety advice on this site assumes you already have a working HMO. This one is for the stage before that: the...